
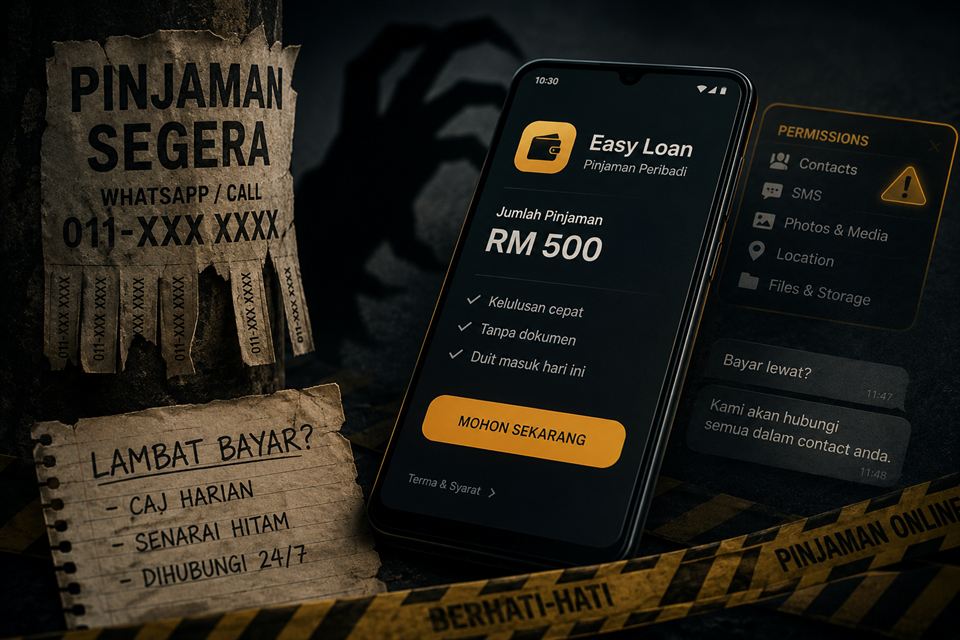
Ah Long got an app now?
Remember those Ah Long ads on tiang lampu?
PINJAMAN SEGERA.
One phone number underneath.
Sometimes half the paper already koyak.
Now they do not really need the tiang anymore.
The offer can come straight to your social media feed: quick loan, easy approval, no complicated paperwork.
Some will bring you to WhatsApp, a website, or even ask you to install an Android app.
When you are short of a few hundred ringgit before payday, memang tempting.
The scary part is not only the interest
With some suspicious loan apps, the bigger question is what you are allowing into your phone.
Contacts.
Photos.
Location.
Files.
You might think, "Never mind lah, I just need RM500."
But if things go wrong, you may have given someone much more than your IC and phone number.
That is why installing an APK sent through WhatsApp, Telegram, or a random website should immediately raise a red flag.
Bank Negara Malaysia also warns that suspicious third-party apps, including APK files, can give scammers access to your phone.
And then there is the repayment.
A small loan does not necessarily stay small when you are dealing with an unlicensed lender.
KPKT states that licensed Community Credit lenders are subject to limits: up to 12% annual interest for secured loans and 18% for unsecured loans.
Complaints involving unlicensed moneylenders, meanwhile, should go directly to PDRM.
Before you tekan "Apply"
There is actually an easy check many Malaysians probably do not know about.
KPKT has i-KrediKom, where you can search whether a Community Credit company is licensed.
You can also find information about borrower rights and make complaints.
If someone gives you a bank account or phone number that looks suspicious, PDRM's Semak Mule is another useful check before transferring money.
Five minutes of checking is worth it.
Especially when the advertisement is pushing you to apply now.
But we cannot put everything on the borrower
"Do not fall for scams" is easy advice to give.
But people looking for emergency loans are usually looking because something has already gone wrong.
Gaji belum masuk.
Car repair.
Medical expenses.
Family emergency.
That is exactly when people make decisions under pressure.
Government agencies already provide verification and reporting channels, but perhaps the next step is making them much harder to miss.
Imagine if checking a lender was as easy as checking a restaurant on Google:
Type the company or app name and immediately get LICENSED, UNLICENSED, or WARNING.
Social media platforms and app stores could also be pushed to respond faster to illegal lending advertisements.
And loan apps asking for excessive permissions deserve much closer scrutiny.
Why exactly does a RM500 loan need access to your entire contact list?
The technology has changed.
Consumer protection needs to keep up with it.
Because Ah Long may look different today.
But putting it inside an app does not suddenly make it legitimate.
Where Malaysians can check
Before borrowing: Search the lender through KPKT i-KrediKom.
Suspicious phone number or bank account: Check PDRM Semak Mule.
Licensed financial institutions: Check Bank Negara Malaysia's Financial Sector Participants directory and Financial Consumer Alert information.
Unlicensed moneylender / Ah Long: Report it to PDRM.
Already transferred money in a suspected scam: Contact your bank immediately and call NSRC 997. Bank Negara Malaysia says victims should also lodge a police report.